Legal Counsel – Secondary Legislation – Public Notices
25 September 2026 – Tax Administration Act, 2011: Public Notice in Government Gazette 55438 of 25 September 2026: Notice 7958 extends the date by which a provisional taxpayer, who received an automatic assessment in terms of paragraph 3(3) of the Notice to submit returns may request a reduced or additional assessment.
Customs – Registration, Licensing and Accreditation
25 September 2026 – The facility codes used in Box 30 on the Goods Declaration has been updated to include details of the terminal for Port Dynamics (Pty) Ltd., located in Durban.
This addition enables Customs to transmit electronic messages communicating the status of the consignment to these facilities.
SARS Digital platform upgrades on 26 September 2026
25 September 2026 – Achieving our Vision of a smart, modern SARS with unquestionable integrity that is trusted and admired is of paramount importance. Pivotal to the delivery of our vision are our digital platforms and technology infrastructure. To provide clarity and certainty, make it easy for taxpayers and traders to comply with their obligations and building public trust and confidence, our technology assets must demonstrate the highest levels of availability, robustness and security.
In accordance with our Vision and Strategic Objectives, which include modernising our systems to provide Digital and Streamlined online services, we are hard at work ensuring that our digital platforms and technology infrastructure are available, robust and secure, by performing regular upgrades, enhancements and maintenance.
Considering the above, SARS Digital platform maintenance is scheduled for:
Saturday, 26 September 2026 from 17h00 to 23h00.
During this time, you may experience intermittent service interruption on our eFiling, Tax and Customs Digital Platforms.
Enhancements to AEOI Reporting
23 September 2026 – SARS is enhancing its systems to implement the Common Reporting Standard (CRS) amendments introduced through CRS Schema 3.0 by the Organisation for Economic Co-operation and Development (OECD). These enhancements are intended to strengthen tax transparency, improve data quality, and enhance reporting requirements for South African financial institutions and SARS.
To enhance SARS’s third-party data environment, the following changes have been introduced:
Null Submissions
For active RFIs with no reportable information for a reporting period:
- A system-generated null-submission indicator has been introduced for SARS internal processing.
- The requirement to submit an FTI02 declaration after a successful FTI01 null submission has been removed.
- A Submitting Entity may include up to 20 RFIs in a single FTI01 submission.
Full Data Submissions
Key enhancements include:
- Bringing certain new financial products and institutions into scope, including e-money products, payment institutions, digital wallet platforms and central bank currency accounts.
- Strengthening due diligence obligations through robust self-certification processes and tax residency identification.
- Enhancing taxpayer and controlling person information to improve completeness.
- Improving Tax Identification Number (TIN) information.
- Strengthening data quality standards to increase accuracy and usability.
While these enhancements are expected to have minimal impact on SARS’s day-to-day operations and employees, they will support greater use of high-quality information, more effective compliance monitoring, improved identification of offshore tax non-compliance, and enhanced revenue collection.
The following external guide has been updated:
Refer to the latest external BRS for AEOI: CRS & FATCA reporting:
Updated: SARS Service Centres open on Saturdays
23 September 2026 – Selected SARS service centres will open on Saturdays to assist taxpayers with filing their Income Tax returns ahead of the Individual Filing Season deadline of 23 October 2026.
The table below provides the details:
Changes: Randburg Service Centre has been added to the schedule.
Service Centres |
Saturdays |
Hours |
Mthatha |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
| 24-Oct | 08:00-13:00 | |
East London |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
| 24-Oct | 08:00-13:00 | |
Gqeberha |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
| 24-Oct | 08:00-13:00 | |
Kariega |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
| 24-Oct | 08:00-13:00 | |
Alberton |
||
| September | 05-Sept | 08:00-13:00 |
| 12-Sept | 08:00-13:00 | |
| 19-Sept | 08:00-13:00 | |
| 26-Sept | 08:00-13:00 | |
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Springs |
||
| September | 12-Sept | 08:00-13:00 |
| 19-Sept | 08:00-13:00 | |
| October | 10-Oct | 08:00-13:00 |
| 17-Oct | 08:00-13:00 | |
Ashlea Gardens |
||
| October | 10-Oct | 08:00-13:00 |
| 17-Oct | 08:00-13:00 | |
Pretoria CBD |
||
| September | 12-Sept | 08:00-13:00 |
| 26-Sept | 08:00-13:00 | |
| October | All Saturdays | 08:00-13:00 |
Newtown, Johannesburg |
||
| September | 05-Sept | 08:00-13:00 |
| 19-Sept | 08:00-13:00 | |
| 26-Sept | 08:00-13:00 | |
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Doringkloof |
||
| September | 05-Sept | 08:00-13:00 |
| 12-Sept | 08:00-13:00 | |
| 19-Sept | 08:00-13:00 | |
| 26-Sept | 08:00-13:00 | |
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Edenvale |
||
| September | 19-Sept | 08:00-13:00 |
| 26-Sept | 08:00-13:00 | |
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Randburg |
||
| October | 17-Oct | 08:00-13:00 |
Mbombela |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
eMalahleni |
||
| September | 05-Sept | 08:00-13:00 |
| 12-Sept | 08:00-13:00 | |
| 19-Sept | 08:00-13:00 | |
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Standerton |
||
| October | 03-Oct | 08:00-13:00 |
| 10-Oct | 08:00-13:00 | |
| 17-Oct | 08:00-13:00 | |
Rustenburg |
||
| Sept-26 | 12-Sept-26 | 08:00-12:00 |
| 26-Sept-26 | 08:00-12:00 | |
| Oct-26 | 03-Oct-26 | 08:00-12:00 |
| 10-Oct-26 | 08:00-12:00 | |
| 17-Oct-26 | 08:00-12:00 | |
Mmabatho |
||
| Sept-26 | 26-Sept-26 | 08:00-12:00 |
| Oct-26 | 10-Oct-26 | 08:00-12:00 |
| 17-Oct-26 | 08:00-12:00 | |
Klerksdorp |
||
| (Note: Klerksdorp only open on Saturdays for return submissions, update of details and eFiling contact details update.) | ||
| Sept-26 | 05-Sept-26 | 08:00-12:00 |
| 19-Sept-26 | 08:00-12:00 | |
| Oct-26 | 03-Oct-26 | 08:00-12:00 |
| 10-Oct-26 | 08:00-12:00 | |
| 17-Oct-26 | 08:00-12:00 | |
Cape Town |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Bellville |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Mitchells Plain |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Paarl |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Worcester |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Beaufort West |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
George |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October | 17-Oct | 08:00-13:00 |
Durban |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October 2026 | 17-Oct | 08:00-13:00 |
Newcastle |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
| October 2026 | 17-Oct | 08:00-13:00 |
Pietermartizburg |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
Pinetown |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
Port Shepstone |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
Richards Bay |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
Umhlanga |
||
| September | 26-Sept | 08:00-13:00 |
| October | 03-Oct | 08:00-13:00 |
| October | 10-Oct | 08:00-13:00 |
Latest Government Connect newsletter is now available
23 September 2026 – This edition highlights key dates and requirements for taxpayers, employers, trusts, and third-party data providers, including Trust Filing Season, bi-annual Third-Party Data submissions, Employer Interim Reconciliation, and the Individual Filing Season deadline. It also covers extended Saturday opening hours at selected SARS service centres.
Find guidance on the Voluntary Disclosure Programme, Tax Compliance Status, and international transfers, as well as a new secure option to update contact details on eFiling without logging in. Stakeholders are invited to comment on VAT Modernisation by 16 October 2026. We encourage readers to note the key updates and take the necessary action within the prescribed timeframes.
Latest Tax Practitioner Connect newsletter is now available
23 September 2026 – This edition highlights key dates and requirements for taxpayers, employers, trusts, and third-party data providers, including Trust Filing Season, bi-annual Third-Party Data submissions, Employer Interim Reconciliation, and the Individual Filing Season deadline. It also covers extended Saturday opening hours at selected SARS service centres.
Find guidance on the Voluntary Disclosure Programme, Tax Compliance Status, and international transfers, as well as a new secure option to update contact details on eFiling without logging in. Stakeholders are invited to comment on VAT Modernisation by 16 October 2026. We encourage readers to note the key updates and take the necessary action within the prescribed timeframes.
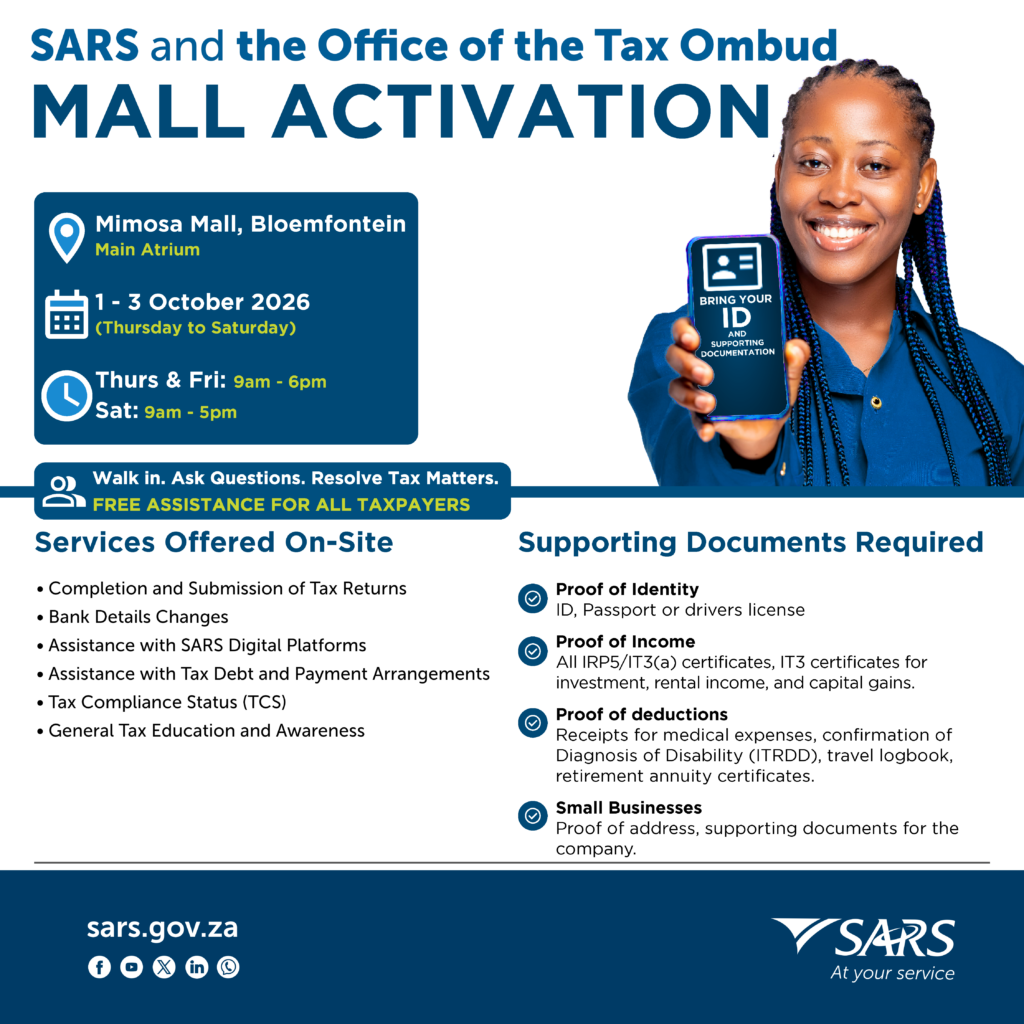
Mimosa Mall in Bloemfontein – SARS and Office of the Tax Ombud visit from 1 – 3 October 2026
23 September 2026 – SARS and the Office of the Tax Ombud will be visiting the Mimosa Mall in Bloemfontein to assist taxpayers with tax related matters.
- Venue: Mimosa Mall, Bloemfontein (main Atrium)
- Dates & times: Thursday, 1 October & Friday, 2 October from 9:00 – 18:00 and Saturday, 3 October from 9:00 – 17:00
Legal Counsel – Dispute Resolution & Judgments – High Court 2028-2026
23 September 2026 – Tax Administration Act, 2011: Cuba Dumakude v Bidvest Bank Limited and Another (054716/25) [2026] ZAGPPHC (8 September 2026)
The principal issues are as follows:
- Whether SARS was correct to issue a third-party notice to Bidvest Bank.
- Whether SARS was correct not to issue a final demand prior issuing the notice
- Whether the applicant was entitled to the funds held by Bidvest Bank
VAT Modernisation Consultation Paper Now Available in Additional South African Languages
22 September 2026 – SARS has published translated versions of the VAT Modernisation Consultation Paper in several South African languages for greater accessibility and stakeholder participation. Additional language versions will be published as they become available. The language version is indicated in the name of the link provided. Interested parties are invited to review the proposals and submit comments by 16 October 2026.
To access the VAT Modernisation Consultation Paper in different languages, click on the links below:
- VAT Modernisation Consultation Paper (English)
- VAT Modernisation Consultation Paper (Afrikaans)
- VAT Modernisation Consultation Paper (isiXhosa)
- VAT Modernisation Consultation Paper (isiZulu)
- VAT Modernisation Consultation Paper (Sepedi)
- VAT Modernisation Consultation Paper (Sesotho)
- VAT Modernisation Consultation Paper (Setswana)
- VAT Modernisation Consultation Paper (Siswati)
- VAT Modernisation Consultation Paper (Xitsonga)
- VAT Modernisation Consultation Paper (IsiNdebele)
- VAT Modernisation Consultation Paper (Tshivenda)
For more information, see the VAT Modernisation webpage.
Excise: Enhanced Diesel Refund Registration
22 September 2026 – As part of the ongoing Customs Modernisation Programme, Diesel Refund registration is being separated from VAT registration. A new automated platform for Diesel Refund Registration has been developed and was implemented on 18 September 2026. In addition, the Diesel Refund Relationship Management function has been implemented on eFiling. With these enhancements:
- Clients will be able to submit Diesel Refund Registration applications through the following channels:
- eFiling; and
- Customs and Excise Branch Office(s).
- Branch front end agents will capture the applications on behalf of the client
- On the SARS Online Query System (SOQS) clients will be able to:
- Obtain their Diesel Refunds Registration Number;
- Request Documents; and
- Check Diesel Refund Registration Status.
- The Relationship Management function enables clients to formally declare, manage and maintain relationships linked to their Diesel Refund registration.
For more information, see the:
- Guide to Diesel Refund Relationship Management
- Diesel Refund Scheme webpage
- Missed the recent Diesel Refund webinar? Watch the SARS TV recording in your own time. See the presentation shared in the webinar here.
Global Minimum Tax: New Administration Capabilities for Affected Multinational Enterprise Groups
21 September 2026 – SARS has improved its Global Minimum Tax (GMT) administration to help affected Multinational Enterprise (MNE) Groups meet their obligations under the Global Anti-Base Erosion (GloBE) Rules.
These improvements form part of South Africa’s commitment to international tax transparency, tax certainty, and cooperation between tax jurisdictions. The enhanced environment supports the exchange of information between participating jurisdictions; local administration of foreign submissions; payment processing; assessment administration; refunds; compliance management; and taxpayer support.
What Is Changing?
GMT administration is expanding beyond registration and filing to support the full compliance journey of affected MNE Groups.
International Information Sharing
GMT is an international tax framework that relies on participating jurisdictions sharing information about affected MNE Groups.
SARS can now receive GMT information submitted in foreign jurisdictions and exchange information with participating tax administrations through established international exchange processes. This supports the validation of information, compliance, and the consistent application of GMT obligations across jurisdictions.
GMT03 Declarations
SARS has introduced the GMT03 declaration process for circumstances where GMT information is submitted by a foreign entity filing on behalf of a South African entity.
If information has already been submitted in another jurisdiction and subsequently exchanged with SARS, a South African entity may still be required to submit a GMT03 declaration to meet local administration and payment requirements.
GMT03 allows to SARS:
- Recognise information received through international information-exchange processes.
- Generate a South African GMT Payment Reference Number (PRN).
- Administer local liabilities where applicable.
- Support payment processing and taxpayer correspondence.
- Validate information received from different sources.
Payment Administration
The updated GMT administration process introduces payment-administration capabilities linked to GMT PRNs. Where payment is required, taxpayers must use the correct GMT PRN to ensure accurate payment allocation and processing. The process also supports payment validation and administration linked to GMT obligations.
Assessments and Compliance Administration
The enhanced Global Minimum Tax environment introduces capabilities that support:
- Revised assessments
- Estimated assessments
- Assessment notices
- Validation outcome correspondence
- Requests for correction and discrepancy-management processes
When information submitted by a taxpayer differs from information received through international exchange mechanisms, SARS may issue notices or request correction before the matter can be finalised.
Administrative Penalties
Administrative penalties now form part of the GMT compliance framework. These processes support the administration of penalties for non-compliance with filing and notification obligations. The GMT compliance framework also supports recurring penalties where applicable, as well as established processes relating to penalty review, remission, and dispute management.
Refund Administration
Refund administration applies where credits arise and taxpayers request a refund. Refund requests remain subject to applicable validation, verification, and authorisation before payment can be made.
What Affected MNE Groups Need to Do
Affected MNE Groups should take the following actions:
- Review Your GMT Obligations
Determine whether your group falls within the scope of GMT and whether obligations are being fulfilled through local filing, foreign filing, or a combination of both.
- Understand Whether GMT03 Applies to your Organisation
If a foreign filing entity submits GMT information on behalf of a South African entity, determine whether a GMT03 declaration is required to support South African administration and payment obligations.
- Coordinate Internal GMT Matters Effectively
Local entities should maintain regular communication with nominated filing entities to understand and manage submissions, exchanged information, and payment obligations.
- Monitor SARS Correspondence
Taxpayers should carefully review and respond to:
- Acknowledgement letters
- Validation outcome letters
- Notices of assessment
- Requests for correction
- Penalty notices
- Other GMT correspondence issued by SARS
- Use The Correct Payment Reference Number (PRN)
When payment is required, taxpayers must use the correct GMT PRN to avoid payment-allocation problems and delays in processing.
- Meet Filing, Notification, and Payment Obligations
Affected taxpayers should meet all filing, notification, and payment obligations within the applicable timeframes and should answer correspondence received from SARS promptly to avoid administrative penalties.
What to Expect Next
SARS is committed to supporting taxpayers throughout the implementation of these requirements. Additional guidance, including detailed instructions and technical specifications, will be released to further support taxpayers and provide clarity on the practical application of the requirements.
Affected stakeholders are encouraged to consult the GMT landing page for approved guidance and frequently asked questions.
SARS looks forward to partnering with stakeholders to facilitate a smooth implementation and encourage consistent compliance among all affected taxpayers.
GMT related enquiries are managed via: [email protected]
Customs Weekly List of Unentered Goods now available
21 September 2026 – The state provides state warehouses for the safekeeping of goods. These are managed by Customs. The purpose of this list of unentered goods is to notify the importer, exporter and any other person that has interest in the goods that the goods have been taken up into the State warehouse and if they remain unentered they will be disposed in accordance with the provisions of the Customs & Excise Act.
See the latest Customs Weekly List of Unentered Goods here.
Employer Interim Filing Season opens today 21 September 2026
21 September 2026 – The Employer Interim Reconciliation submission period opens on 21 September 2026 and closes on 31 October 2026. During this period, employers must reconcile their declarations for the period 1 March 2026 to 31 August 2026 and submit their EMP501 declarations through eFiling or e@syFile™ Employer.
Employers are encouraged to prepare early by:
- Ensuring payroll and employee information is accurate and up to date.
- Confirming that all employees have valid Income Tax reference numbers.
- Downloading and using the latest e@syFile™ Employer version once it is released.
- Reviewing the latest PAYE Employer Reconciliation Business Requirements Specification (BRS).
Submitting accurate declarations on time lets employers avoid penalties, interest, and unnecessary administrative work. After submitting an EMP501 declaration, employers should also check their submission status and PAYE Dashboard to confirm that the reconciliation was successfully processed.
Don’t just submit. Confirm. Activate the Power of DONE.
The following enhancements have been implemented for the interim PAYE Filing Season:
- New source codes have been added;
- Changes to field types and validations;
- Enhancements to EMP201 Return;
- Enhancements to EMP501 Reconciliation;
- Revised declaration function;
- New rules for e@syFile software;
- Enhancements to SARS letters and forms.
New source codes have been added:
- 3061 – Additional Id Number;
- 3067 – Expired Asylum Seeker Permit Number;
- 3071 – Expired passport number;
- 3076 – Expired passport country of issue;
- 3081 – Country of Birth.
Changes to field types and validations:
- Source codes 3622/3672 – Long Service Cash Award;
- Source code 3696 – Gross non-taxable income;
- Source code 3699 – Gross employment income (taxable);
- Source code 3835/3885 – Long Service Award;
- Source code 3922 – Compensation in respect of death during employment;
- Source code 4118 – The sum of the ETI amounts calculated;
- Source code 4150 – Reason code for IT3(a) certificate;
- Source code 4588 – The total amount repaid by the employee in the tax year for a s11(nA) recoupment.
Enhancements to EMP201 Return
- Systematically initiate a pre-population when the user tries to submit a saved EMP201 return after 30 days to update the return with the latest information.
Enhancements to EMP501 Reconciliation
- A reconciliation received acknowledgement will be sent to the submitting channel.
- eFiling and e@syFile will update the status of the reconciliation to indicate to the user that the reconciliation has been received and is being processed.
- Employment Taxes Validation (ETV) can now check the tax directive status.
- The employer will be requested to complete a satisfaction survey after submitting an EMP501 reconciliation.
Revised Declaration Function
- All text boxes on the “Additional info” tab will be enhanced to be spellchecked.
- A revised declaration for Employment Tax Incentive (ETI) will be sent for an internal review.
New rules for e@syFile software
- The rules for the e@syFile password will be aligned with the rules for eFiling.
- The requirement for re-authentication will be revised.
Enhancements to SARS letters and forms
- All letters and forms will be enhanced to align with the new PDF generated service.
e@syFile Release Notes:
- See the updated Release Notes here.
- The update from version 8.0.1 to 8.0.2 requires a full uninstall and reinstall from the eFiling website.
- New button added to the PAYE Dashboard that links to the e@syFile Technical FAQ’s.
- New ITReg indicator added to Employee Admin for additional information to be captured.
- New button added on the Reconciliation page that allows users to log a ‘Pending Submission’ query
- Directly from the application.
- New option added to the Reconciliation Status Dashboard Action tab to allow users to generate an EMP601.
- New tab System Info added to Utilities menu.
For more information, see the e@syFile FAQs.
The updated guides are:
-
- PAYE-AE-06-G06 – Guide for Codes Applicable to Employees Tax Certificates 2027 – External Guide
- PAYE-AE-06-G07 – Guide for Validation Rules Applicable to Reconciliation Declarations 2027 – External Guide
- PAYE-AE-06-G08 – Guide for Completion and Submission of Employees Tax Certificates 2027 – External Guide
- EMP-GEN-02-G01 – A Guide to the Employer Reconciliation Process – External Guide
- PAYE-easyFileG01 – e@syfile™TC Employer Guide – External Guide
Trust Filing Season opens on 19 September 2026
18 September 2026 – The 2026 Trust Filing Season opens on 19 September 2026. Trustees and representative taxpayers should ensure that the trust is registered for income tax; the trust registered details are correct; and all financial records and supporting documents are ready before completing the Income Tax Returns for Trusts (ITR12T). Trustees remain accountable for the trust’s tax compliance, even when assisted by a tax practitioner. Prepare early, verify all information, and submit an accurate ITR12T through SARS eFiling by 22 January 2027.
Several legislative, form, and process changes have been introduced for the Trust Filing Season 2026, including but not limited to the following:
Enhanced Taxpayer Experience
- An automated SMS to remind taxpayers to file on time and pay outstanding debt;
- A satisfaction survey is included as part of the Trust Income Tax Return (ITR12T);
- The taxpayer is now able to amend the Masters Reference Number from the ITR12T;
- Newly enabled continuous saving of the ITR12T return.
Legislative Requirements
- The information on the “Income Vested Containers” will now be pre-populated with the IT3(t) information on the ITR12T as well as the Personal Income Tax Return (ITR12) and the Company Income Tax Return (ITR14).
- The beneficiary schedules of the ITR12T will also be pre-populated with the information from the IT3(t).
- A new container to determine the impact and analyse the utilisation of the loss limitation per section 25B(4) to (6) of the Income Tax Act No. 58 of 1962 is included on the ITR12T.
- The Return Control Table (RCT) is now aligned to indicate that all trusts are required to file returns.
- The questions in relation to the “Beneficial Ownership” container have been enhanced to also cater for founders that are legal entities.
- The “Beneficial Ownership” container has been made optional for Collective Investment Schemes (CIS) trusts.
- The email address of the tax practitioner is now a compulsory field.
See the updated Guides:
- Step by Step Guide to Complete your Trust Return via eFiling
- Comprehensive Guide to the Income Tax Return for Trusts
For more information, see the Trusts webpage and FAQs for Trusts.
Frequently Asked Questions on VAT Modernisation
18 September 2026 – SARS developed FAQs to answer common questions about SARS’s proposed VAT modernisation. It explains the Digital VAT Model, how implementation may work, and what different business segments may need to consider. It should be read together with the Consultation Paper.
VAT Deregistration for Schools
18 September 2026 – With effect from 1 January 2026, supplies made by schools registered under the South African Schools Act, 1996 are exempt from VAT, except to the extent that a school carries on approved welfare activities as a welfare organisation. As a result, affected schools no longer qualify to remain registered as VAT vendors and must apply for cancellation of their VAT registration.
SARS will issue letters to schools to notify them of the legislative change and outline the required actions, supporting documents and submission channel.
Required Actions by Schools
- Affected schools must complete the VAT123e application for cancellation of registration.
- The reason for cancellation under Section A must be indicated as: “All enterprise activities have ceased on 31 December 2025”.
- The total net value of business assets held as at 31 December 2025 must be completed under Section B.
- The completed VAT123e must be emailed to [email protected] with the subject line: “VAT deregistration – Schools”.
- Where a school requires a deferment or instalment arrangement for exit VAT, a written application/payment arrangement request must also be submitted.
For more information see:
- FAQs for operational matters relating to schools exiting the VAT system
- VAT Reference Guide – Schools Exiting the VAT System;
- Media Statement issued to schools.
Watch a recording of the Diesel Refund Registration webinar
18 September 2026 – Missed the webinar? SARS held a webinar on Friday, 18 September 2026 for diesel-refund users, diesel sellers, fuel suppliers, contractors, intermediaries, and tax practitioners on the release of the Diesel Refund Registration Programme.
Watch the SARS TV recording in your own time.
See the presentation shared in the webinar here.
The release is planned for 18 September 2026. More detail will be shared soon.
It introduces the Diesel User Dashboard capability and completes the end-to-end registration solution. The webinar will explain the changes, who is affected, and the steps stakeholders should take to prepare.
Key Changes
- Diesel Refund registration is moving from a VAT-linked model to a dedicated Diesel Refund Registration System on eFiling.
- Existing diesel-refund users must register on the new solution. Registration is not automatic.
- Diesel sellers must register so that diesel-refund users can create and manage seller relationships electronically.
- A dedicated dashboard will provide visibility of applications, registrations, and seller relationships.
What You Need to Do
- Diesel-refund users/buyers: Prepare to register through eFiling; ensure your SARS legal-entity profile is valid and confirmed; gather business-activity information; and be ready to create seller relationships.
- Diesel seller: Register as a diesel seller and ensure your details are accurate so users can establish and validate relationships with you.
What the Webinar covered
- The purpose and phased implementation of the Diesel Refund Registration Programme.
- Registration requirements for diesel-refund users and diesel sellers.
- How electronic diesel seller and user relationships work together.
- Steps to prepare, including legal-entity profile readiness and required business information.
- The dedicated dashboard, available support, and a live question-and-answer session.
Legal Counsel – Secondary Legislation – Rules Amendments 2026
18 September 2026 – Customs and Excise Act, 1964: Publication of rules amendments notice R7921 in Government Gazette 55406 of 18 September 2026, relate to the following:
- Amendments to rules under sections 75 and 120 in relation to diesel refund registrations (DAR280)
Legal Counsel – Secondary Legislation – Tariff Amendments 2026
18 September 2026 – Customs and Excise Act, 1964: Publication details for tariff amendments notices, R7920, R7937, R7938, R7939, R7940 and R7941, as published in Government Gazette 55406 and 55424, of 18 September 2026, are now available.